Monthly Market Commentary

These monthly market commentaries share a synopsis of the U.S. financial markets with intelligent insights.

The Economy is the Stronger Signal

Fact:

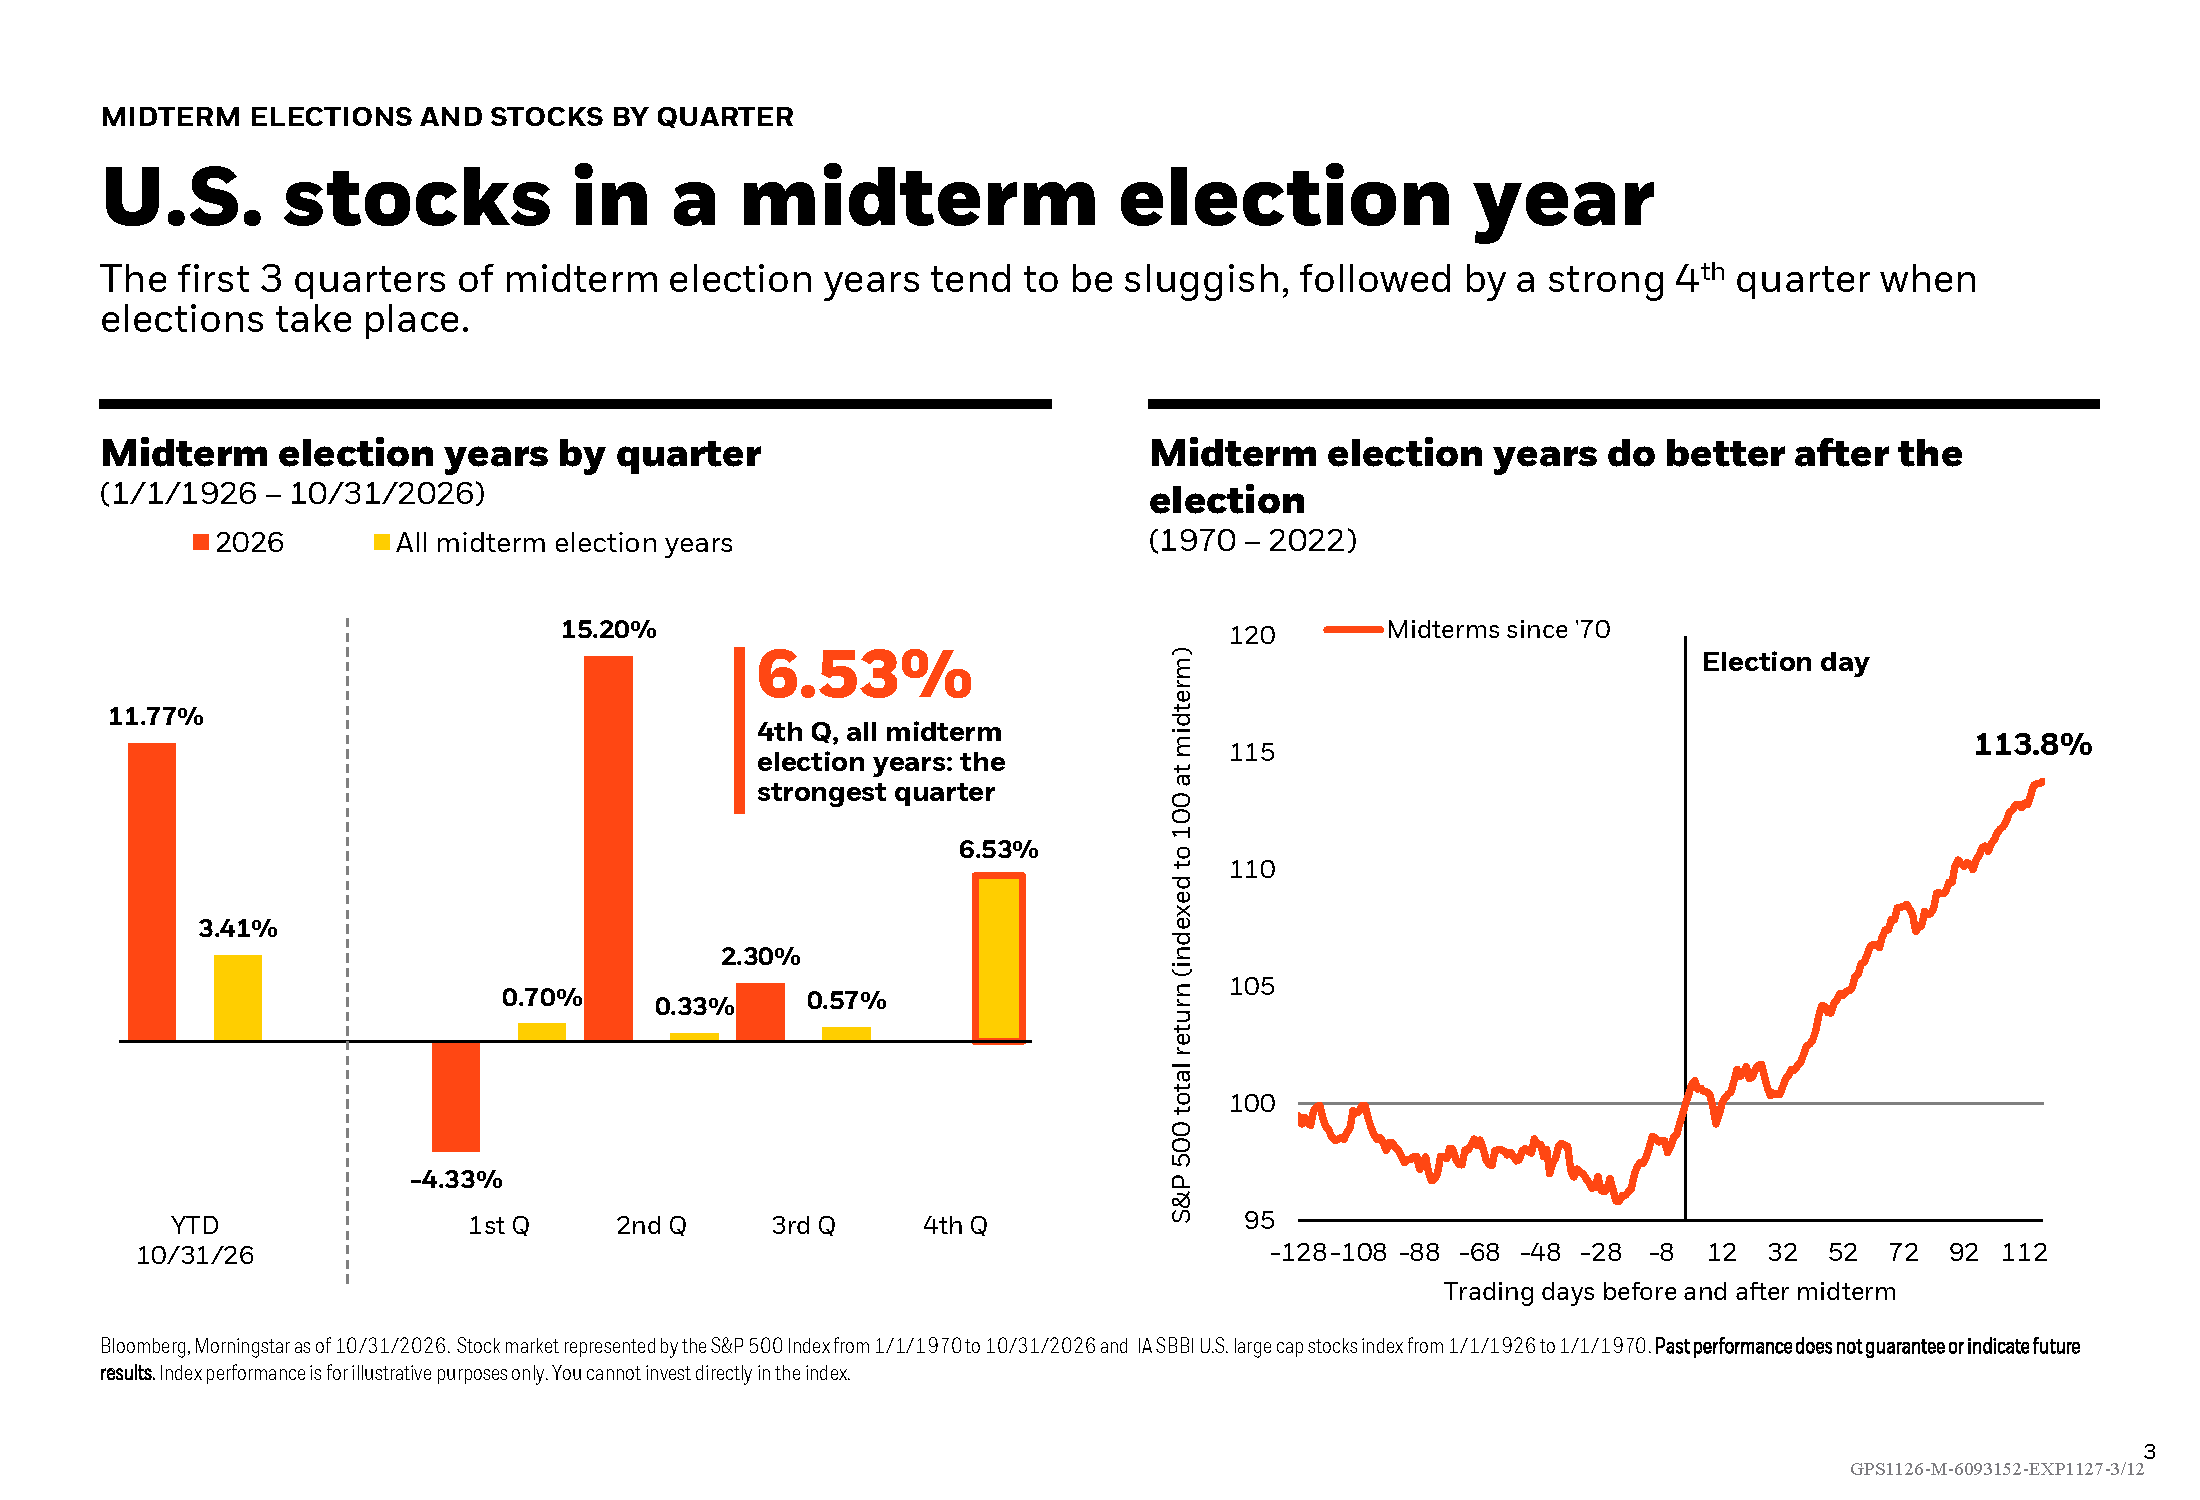
  • In the 12 months following a midterm election, the S&P 500 has been up 15% on average, historically.
  • Since 1950, every 12-month period following the midterms has had a positive return.

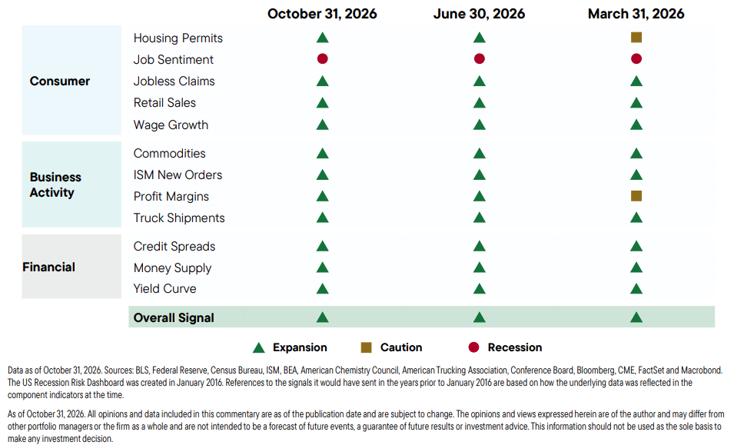
U.S. gross domestic product grew at a 3.4% annualized pace in the third quarter, accelerating from 2.2% in the second quarter. Business investment led the way as the artificial intelligence buildout continues and steady consumer spending provided additional support. Our Recession Dashboard tells a similarly resilient story. 11 of its 12 indicators are flashing expansionary green, with no changes in October, a reading that implies recession odds of only 15% over the next 12 months.

We use 12 different economic indicators to assess the risk of recession.

Each individual indicator can signal expansion, caution or recession in this economy. The signals from each of the 12 indicators are combined into an overall dashboard signal.

The indicators, signals and changes are based on our interpretation of the data. The dashboard is not a crystal ball, but can serve as a tool to evaluate the risk of recession in the U.S. economy.
The Economy is the Stronger Signal

see chart here

Economic Growth Remains Strong in the United States

Consumers remain resilient. We have heard this on most earnings calls the past couple of weeks. The main takeaway has been that the consumer is healthy and supported by a strong labor market, even amid higher gas prices in Q3. Retail sales for September increased 0.8% month-over-month (m/m), versus market expectations of 0.3%, bringing the year-over-year increase to 6.3%,

Initial jobless claims, reported last Thursday, came in slightly below expectations again, and the 4-week average remains below 200,000. This data supports our belief that the labor market remains strong. The September unemployment rate (reported on October 2) was 4.2%.

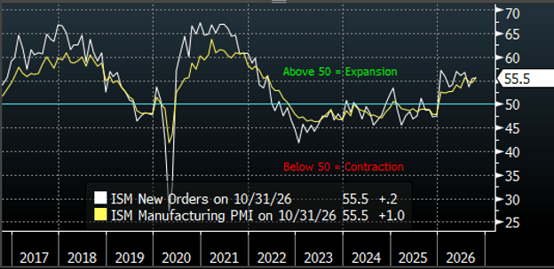
(+) Solid economic data the last couple days. September JOLTs Job Openings hit a 4-mo high, Layoffs declined. In addition, Factory Orders beat estimates, following yesterday's roundly better ISM Manufacturing data. Production, Inventory, and New Orders were all solid and Prices Paid came down a bit. Positive all around and firmly in expansion mode.

"And obviously, we've continued to see the industrial economy with positive ISM through the year. It's been in, kind of, the low to mid-50s, but it's been in expansion territory. So that's been good." - Trucking company Old Dominion Freight Line CFO Adam Satterfield
Economic Growth Remains Strong in the United States

see chart here

Inflation Outlook

Global price pressures rebounded for the first time in 5 months amid the ongoing war in the Middle East and strong AI-related demand worldwide. A surge in energy and transport costs accounted for most of the increase in September, while higher semiconductor and electrical equipment prices also contributed, albeit less than in the prior month.

Led by higher gasoline and other energy prices, the headline U.S. Consumer Price Index (CPI) jumped the most in 6 months. Importantly, the core CPI, which excludes energy and food, also surprised to the upside, the most since April. Higher inflation is eroding consumer purchasing power, as real average hourly earnings continued to decline in September both from the prior month and from a year ago. The upward inflation surprise means that the Federal Open Market Committee (FOMC) will likely maintain a hawkish stance and deliver another rate hike by the end of the year.

October Review

For the month of October, equity results were mixed. A number of the Mag 7 and AI related stocks stumbled enough to drag the S&P 500 down -0.9% for the month, with approximately -2% of that decline coming on the last day. Much of this last day's decline came from disappointing AI related stocks. The Russell 1000 Growth fell -6% for the month, falling -4% on the last day. Conversely, many of the less AI related sectors performed well, with the Russell 1000 Value up 4% for the month. Small cap stocks rose 0.6% for the month. Non-U.S. stocks were down modestly for the month while emerging market stocks fell more due to their high correlation to the AI buildout. Fixed income returns were strong, fueled by interest rates declining 30-35bps across the yield curve. Economic data was mixed with U.S. GDP growing more than 3% in Q3 while inflation metrics ticked higher, with energy costs a leading contributor.

Here are observations on what occurred across the investment markets in October:


Broad Market Performance1

Data as of October 31, 2026
Index Oct YTD 1 Year 3 Year
S&P 500 -0.9 11.8 12.1 23.4
MSCI EAFE -0.7 9.5 13.5 19.8
Bloomberg US Aggregate Bond 2.4 -0.5 -0.7 5.5


Domestic Equity2

  • U.S. large caps slipped in October, with the S & P 500 down -0.9% and the Russell 1000 down -0.7%. Growth sold off sharply (Russell 1000 Growth -6.1%) while value gained (Russell 1000 Value 4.4%). The NASDAQ 100 fell -6.6%, while the S & P 500 Equal Weighted rose +5.0%.  

  • Mid and small caps outperformed large caps in October, with the Russell Mid Cap up +3.2% and the Russell 2000 up +0.6%. Value led growth across both segments, with Russell Mid Cap Value up +5.8% versus -4.4% for Mid Cap Growth. 


International and Global Equities3

  • International equities declined in October, with the MSCI ACWI ex-USA down -2.8%, hurt by emerging markets. Developed markets held up better, with the MSCI EAFE at -0.7%, and value outperformed growth.

  • Emerging markets were the weakest major segment, with the MSCI EM Index falling -8.0%. Growth (-10.2%) lagged value (-5.9%). China declined -7.0% and S. Korea fell -17%.


Fixed Income Markets4

  • Bonds rallied in October, with the Bloomberg U.S. Agg returning +2.4% as interest rates declined. Longer duration sectors led, including longer maturity government bonds (+5.2%) and mortgage backed securities (+3.1%). High yield (+0.3%) and leveraged loans (-0.2%) lagged.


Specialty Markets5

  •  REITs rebounded, with the DJ Equity All REIT up +4.7%. The S & P GSCI gained +4.8% while the Bloomberg Commodity Index was flat. Bitcoin fell -8.2%.


Sectors6

  • Energy (+14.0%), Consumer Staples (+11.6%), Utilities (+10.2%), and Health Care (+9.9%) led in October. Communication Services (-15.1%) and Information Technology (-6.8%) were the only sectors to decline.

Thank you for your trust along your financial journey.

Scott Krase  |  Wealth Manager  |  skrase@GoCGO.com   |  773.255.0411
scott headshot

Helpful Resources

View our Economic Market Minutes: https://www.gocgo.com/market-minute

Financial Planning Webinars: https://www.gocgo.com/market-minute

Firm Website: https://www.gocgo.com/financial-planning-and-wealth-management

Investor Blog: https://www.commonfinancialsense.com/ 

Disclosures & References

Investment Advisory Services offered through Global Retirement Partners, LLC DBA Connor & Gallagher OneSource, an SEC registered investment advisor.

1-6 All data referenced in the table and comments supplied by Morningstar.

This document is a general communication being provided for informational purposes only. It is educational in nature and not designed to be taken as advice or a recommendation for any specific investment product, strategy, plan feature or other purpose in any jurisdiction, nor is it a commitment from Global Retirement Partners, LLC or any of its subsidiaries to participate in any of the transactions mentioned herein. Any examples used are generic, hypothetical and for illustration purposes only. This material does not contain sufficient information to support an investment decision, and it should not be relied upon by you in evaluating the merits of investing in any securities or products. In addition, users should make an independent assessment of the legal, regulatory, tax, credit, and accounting implications and determine, together with their own financial professionals, if any investment mentioned herein is believed to be appropriate to their personal goals. Investors should ensure that they obtain all available relevant information before making any investment. Any forecasts, figures, opinions or investment techniques and strategies set out are for informational purposes only, based on certain assumptions and current market conditions and are subject to change without prior notice. All information presented herein is considered to be accurate at the time of production, but no warranty of accuracy is given and no liability in respect of any error or omission is accepted. It should be noted that investment involves risks, the value of investments and the income from them may fluctuate in accordance with market conditions and taxation agreements and investors may not get back the full amount invested. Both past performance and yields are not reliable indicators of current and future results.

This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance that the views or strategies discussed are suitable for all investors or will yield positive outcomes. Investing involves risks including possible loss of principal. Any economic forecasts set forth may not develop as predicted and are subject to change. References to markets, asset classes, and sectors are generally regarding the corresponding market index. Indexes are unmanaged statistical composites and cannot be invested into directly. Index performance is not indicative of the performance of any investment and do not reflect fees, expenses, or sales charges. All performance referenced is historical and is no guarantee of future results. Any company names noted herein are for educational purposes only and not an indication of trading intent or a solicitation of their products or services. Connor & Gallagher OneSource doesn’t provide research on individual equities. All information is believed to be from reliable sources; however Connor & Gallagher OneSource makes no representation as to its completeness or accuracy.

*Securities offered through LPL Financial, Member FINRA & SIPC. Investment advisory services offered through Global Retirement Partners, LLC DBA Connor & Gallagher OneSource, an SEC registered investment advisor. Connor & Gallagher OneSource and Connor & Gallagher Benefit Services are separate entities from LPL Financial.

Contact Scott

Contact Scott with any questions, or to request a portfolio review.

Scott Krase